
A corporate expense card streamlines spending and gives finance teams real oversight rather than waiting for delayed reports at month end.
Key takeaways
Finance funds a prepaid corporate expense card in advance, so an employee can only spend money finance has already made available.
Company credit cards extend an underwritten credit line, and policy checks have historically happened after the money has gone.
Moving receipt capture and coding to the moment of purchase removes most of the monthly expense claim cycle for employees and finance.
Finance sees each transaction as it happens in a connected card programme, so it can answer budget and fraud questions during the month rather than at close.
Prepaid cards give up the payment float of a credit card, and rebate levels vary by programme. The finance team should choose based on whether control or working capital is the tighter constraint.
What are corporate expense cards?
Corporate expense cards let employees pay for business costs with company money, inside a limit finance sets before the purchase. A connected card programme can also send transaction data to the finance team the moment an employee uses the card.
This article focuses on prepaid or debit-based company cards rather than credit cards. There is no credit line to underwrite and no credit-card statement to wait for.
The Financial Conduct Authority describes electronic money, which is what a prepaid card balance is, as “a prepaid product.” Unlike credit provided through a credit card, “the customer pays for the spending power in advance.”
Expense cards come in two forms:
Physical cards cover purchases made in person, including travel and meals.
Virtual cards handle online purchases and subscriptions. They can be single-use or multi-use, with the latter tied to one supplier where needed.
In both cases, two ceilings cap spending:
The limit finance sets on the card.
The balance available in the company's funding account.
What are the benefits of expense cards?
Prepaid expense cards apply spend control before the payment goes through, while a connected platform can create the accounting record at the same moment.
Every benefit that follows comes from that timing.
1. Easy access to company funds
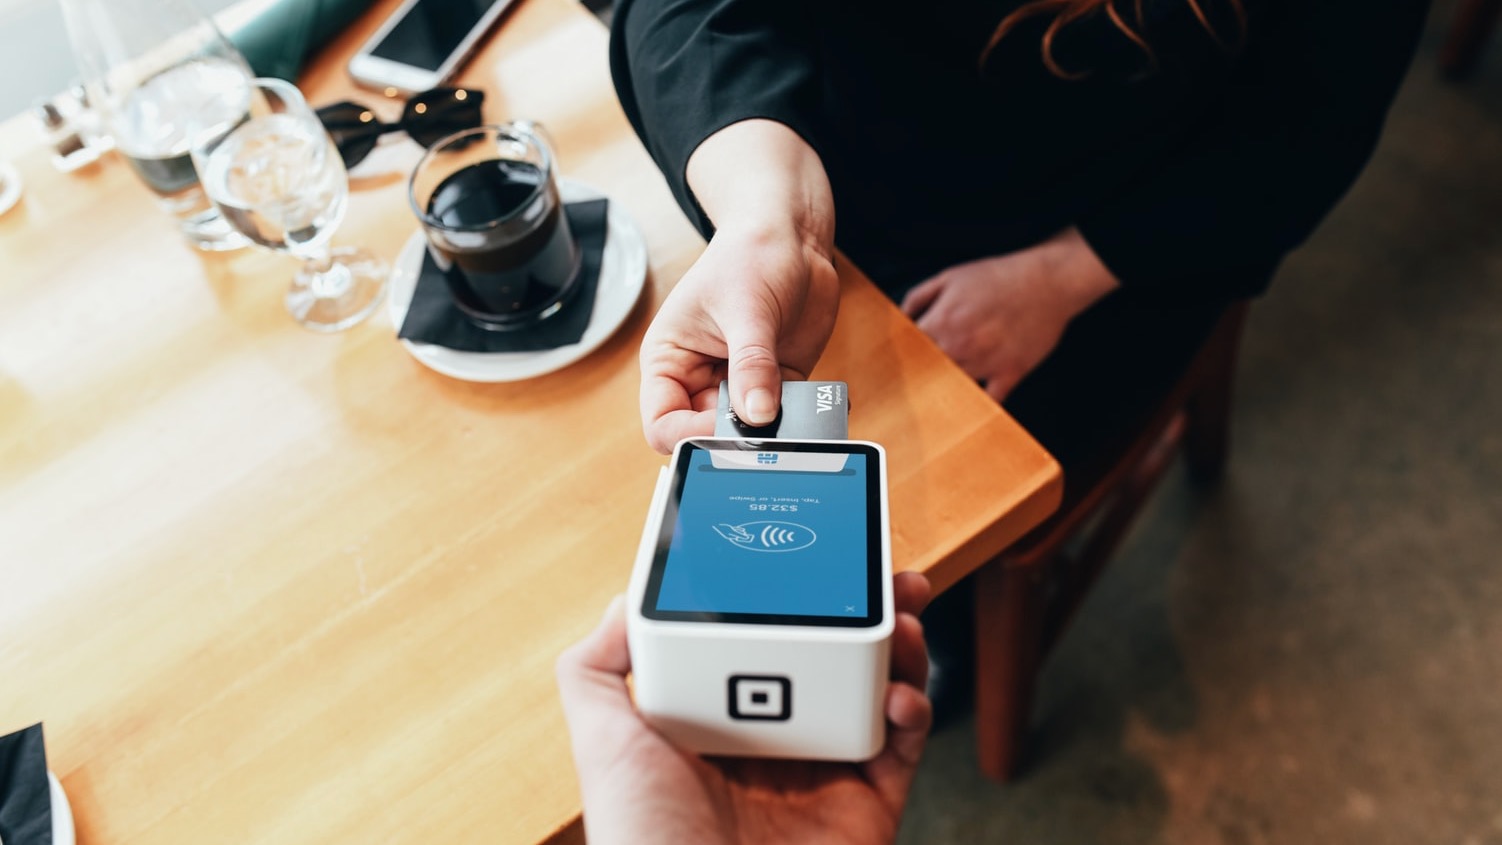
An employee with a corporate expense card can pay for a train ticket or a client lunch without touching their own account. There is no cardholder credit application to submit and no cardholder underwriting to wait for.
Providers can typically issue and fund prepaid cards without a credit application for each employee, although timing depends on the provider's onboarding and card-issuance process.
The alternative to a card is reimbursement, and reimbursement is slow. Conferma surveyed 1,000 UK adults in employment in June 2025 and found the average wait to be reimbursed was 2.5 weeks.
For a new hire or a junior team member, that means a fortnight or more of carrying the company's costs on a personal card. Giving your people business expense cards closes that gap, and it takes the reimbursement run off your finance calendar too.
2. Clear limits on expenses
A prepaid expense card cannot exceed the limit you have set because the issuer declines the transaction at authorisation rather than finance querying it afterwards.
You can set the cap:
Per card.
Per transaction.
Per day.
Per month.
The provider can then apply any change immediately where the programme supports it.
That turns the company expense policy from a document people are asked to remember into a rule the card applies on their behalf. It also gives finance control over spending before the money leaves the account.
The shift is from reviewing spend to preventing it. Kevin Permenter, Senior Research Director at IDC, put it this way in March 2026:
“Expense reports document spending after it happens. The next generation of T&E platforms will help finance control spending before it occurs.”
3. No need for monthly claim forms
Monthly claim forms are unpopular for good reason. Employees hate them, and the traditional expense report process is slow for everyone involved.
With a connected corporate expense card programme, the employee captures the receipt on a phone at the till. The platform matches it to the card transaction and prepares the coding for finance to review.
There is no monthly form to fill in, and the platform reduces the statement reconciliation left for finance.
The hidden costs of that process land on finance, and approval is slow too. The APQC Open Standards Benchmarking, drawn from 5,038 organisations, puts the median at 6.0 calendar days from receiving a claim to approving it and scheduling payment.
That is nearly a week of latency per claim before any money moves.
Spendesk's expense claims module lets the employee capture the receipt from a phone and uses Optical Character Recognition to read the supplier and VAT.
Its Play by the Rules control can block further card spending until the employee submits the required receipt.
Out-of-pocket claims such as mileage or a per diem still exist, but they become the exception rather than the monthly default.
4. Real-time data for finance teams
In a connected card programme, the issuer sends real-time transaction data to the finance team as it authorises each payment.
The data includes the cardholder and transaction details, while the platform can categorise the purchase afterwards. Traditional programmes may rely on a monthly statement, while connected prepaid and modern credit-card programmes can provide transaction data with every purchase.
Delayed visibility is a live problem for UK finance teams. In an April 2025 OFX survey of 150 UK SME finance leaders at companies with 51 to 200 employees, 39% named “lack of real-time visibility into expenses” as a current challenge.
That is the CFO who cannot answer “where is our money going right now?” without commissioning a report that takes days to assemble.
Seeing spend as it happens is also a fraud control because finance sees an unusual transaction in the week the cardholder makes it, rather than in a statement weeks later.
Once card data flows into a spend management tool alongside invoices and claims, budget-versus-actual becomes a live figure rather than a month-end reconstruction.
Are corporate expense cards the best cards for business expenses?
Prepaid expense cards suit teams prioritising control and lower administration, while credit cards retain advantages in payment float and rebates.
Many finance teams therefore use both funding models for different types of spend.
Status quo: the company credit card
A traditional company credit card runs on a credit line the issuer underwrites for the business.
Where the agreement falls within regulated credit rules, the FCA Handbook requires the issuer to make “a reasonable assessment of the creditworthiness of a customer.”
The issuer must do so before entering into a regulated credit agreement or significantly increasing the credit provided. Whether a given commercial card agreement falls within those rules depends on the product and the parties, so check the terms rather than assuming.
Control on a credit card often starts at the programme level. Santander tells UK business account holders that:
“You'll be able to control the amount any additional cardholders spend by setting monthly spending limits.”
Santander also notes that for a limited company, “we may ask you to give a personal guarantee.”
Traditional programmes may still rely on monthly statements, requiring finance to connect each transaction with its receipt and approver afterwards.
Modern credit-card integrations can add real-time controls without replacing the underlying credit line. They can also capture receipts and transaction data.
While purchasing cards address part of this for supplier spend, some employee expenses still flow through shared cards or personal reimbursement.
That reconstruction is where the hours go, and the credit card's advantages are financial rather than operational when the programme lacks a connected spend platform.
CFO.com noted in September 2023 that paying by card “extends the payment terms” by another 20 to 30 days after the bill arrives. It also reported that rebates “average 1% of spend, but could be higher or lower.”
For a business paying large supplier invoices by card, that payment float and rebate are worth keeping.
The modern option: expense cards
Prepaid expense cards apply the rule at authorisation, while a connected platform can create the record in the same second.
That reverses the traditional credit-card statement cycle, although modern credit-card integrations increasingly provide similar operational controls.
Here is how the two funding models differ on the dimensions that change finance's workload.
Corporate expense card vs company credit card: 2026 comparison
Dimension | Company credit card | Corporate expense card, prepaid |
|---|---|---|
Funding | The issuer underwrites a credit line for the business. | Finance loads funds in advance; the issuer extends no credit. |
Setting limits | The issuer sets the programme limit; the company can set monthly sub-limits per cardholder. | Finance sets per-card, per-transaction, daily, or monthly caps. The provider can apply changes immediately. |
Enforcing policy | Traditional programmes review policy after spend; modern integrations can add proactive controls. | The issuer declines a transaction at authorisation if it exceeds the limit or balance. |
Visibility | Traditional programmes may rely on statement-cycle reconciliation; modern integrations can provide real-time data. | A connected programme makes transaction data available as spend happens. |
Eligibility | The issuer assesses creditworthiness and may request a personal guarantee. | The issuer does not underwrite credit for the business or cardholder. |
Working capital | Payment float, with interest if the business does not clear the balance. | Finance ties up funds in advance; there is no float. |
Rewards | Rebates are common; the level depends on the programme. | Rewards vary by programme. |
Exposure when an employee or third party misuses a card | Depends on the liability model in the signed agreement. | Exposure is capped by the loaded balance, with no credit line to exceed. Total exposure for unauthorised transactions, chargebacks, and offline transactions remains subject to the signed agreement. |
For a scaling European finance team, the trade-off is control and data on one side, and float and rebates on the other.
Finance must fund prepaid cards before employees use them, which ties up working capital a credit line would leave free.
A business paying six-figure supplier invoices by card may therefore want to keep a credit facility for that and use expense cards for everyday employee spend.
A rebate does not attach a receipt at the till or decline an out-of-policy purchase, but a connected credit-card platform may provide those controls too.
Online, virtual cards are the natural fit for subscriptions and one-off purchases. It is worth asking a provider how it handles authentication now that new 3DS security checks are common on card payments made online.
Spendesk is an all-in-one spend management platform consolidating company cards, expense management, accounts payable, procurement, and budgeting.
This lets the card transaction and its supporting accounting record live together rather than in separate systems. You can issue a virtual card for a single subscription, cap it, and see the renewal alongside its receipt in the same view.
Spendesk issues prepaid or debit-based cards, and paid plans include unlimited issuance.
Delegate spending and review exceptions
Giving each employee a corporate expense card with its own limit turns your finance team from a checkpoint into a reviewer of exceptions. People who need to spend can spend within rules they can see on the card. You stop approving coffee and start approving the purchases that need judgement.
The rationale behind giving every employee here at Spendesk their own company card applies to most growing teams. The person closest to the purchase is best placed to make it and document it, provided finance sets the guardrails in advance.
For the UK employees who still pay first and claim later, the card changes who carries the financial risk. For finance, it changes when the information arrives, from weeks after the purchase to the second it happens.
Use these questions to size the change for your own team:
How many employees currently pay for work costs personally, and how long do they wait to be repaid?
How many finance hours go into chasing receipts and reconciling statements?
How often does the team find out-of-policy purchases after payment?
If uncontrolled card activity or reimbursement drag is the answer to either question, see how Spendesk's smart company cards apply limits and approval rules before a transaction, giving employees a clear way to spend while finance retains control.
Get a free tour to see the full workflow, from issuing a card to exporting the coded transaction.
Move purchase funding out of employees' pockets
The practical goal is to stop routine work purchases from becoming personal loans from employees to the company, while giving finance the record early enough to act on it. A prepaid expense-card programme fits that goal when control and timely data matter more than payment float.
Where working capital or rebates matter more, a connected credit-card programme may remain the better fit. Either way, the record should reach finance when the purchase happens, not weeks after the employee has funded it.
Frequently asked questions about corporate expense cards
These answers cover liability, fund protection, residual reimbursement claims, and virtual-card use.
Who is liable if an employee misuses a corporate expense card?
A prepaid card carries no credit line, so unlike a card with a five-figure credit limit it cannot go into a negative balance, creating a meaningfully different risk profile. That said, a company's total exposure for unauthorised transactions, offline transactions, and chargebacks still depends on the specific terms of the signed agreement.
Whether statutory protections and liability caps apply to your organisation will depend on your entity type and the wording of your contract. Confirm the position for your specific entity and agreement with your provider and against the current FCA approach document for your entity type.
Are the funds on a prepaid corporate expense card protected if the provider fails?
Prepaid card balances are electronic money, and the FCA is clear that:
“Funds held by payment and e-money firms are not directly protected by the Financial Services Compensation Scheme (FSCS).”
Instead, firms must safeguard those funds, which is a distinct and separate arrangement from FSCS protection. Whether and how any protection applies in practice depends on the issuer, its legal entity, and how it holds the funds.
The FCA's supplementary safeguarding rules came into force in 2026, and this is a time-sensitive position subject to change. Readers should verify the current position against up-to-date FCA guidance rather than treating any stated commencement date as settled. Before relying on any protection claim, check the provider's legal entity and permissions on the FCA Financial Services Register, or the equivalent national register for an EEA issuer.
Can corporate expense cards replace reimbursements entirely?
Not entirely. Employees claim mileage and per diem allowances because they receive the payment rather than a merchant. A card-first company still needs a claims workflow for those categories. The difference is that the workflow handles a small residue rather than every purchase.
Do corporate expense cards work for software subscriptions and online purchases?
Yes, through virtual cards. A subscription virtual card tied to one supplier keeps the renewal visible in the spend data, while card controls let finance manage future charges subject to the provider's terms and payment rules.
A single-use virtual card expires after one payment, which limits exposure if the card details leak. Whether Strong Customer Authentication applies to a given payment depends on the issuer, merchant, transaction type, and jurisdiction. Confirm with the provider how authentication is handled for its virtual cards.
Curious how Spendesk works?
Try an interactive demo to see spend control and approvals end-to-end.
Get a free tour
Maxime Reding
Originally from Luxembourg and educated at the Rotterdam School of Management, he brings a sharp analytical mindset and a background in strategic management to our finance team. Maxime joined Spendesk in 2021 and has grown steadily through the ranks since, becoming our resident finance engineer.


